All Categories
Featured
Comparing PPO and HMO Health Insurance Explained
Indexed Universal Life Benefits for Retirement


2026 Whole Life Insurance Rates for Families
Table of Contents
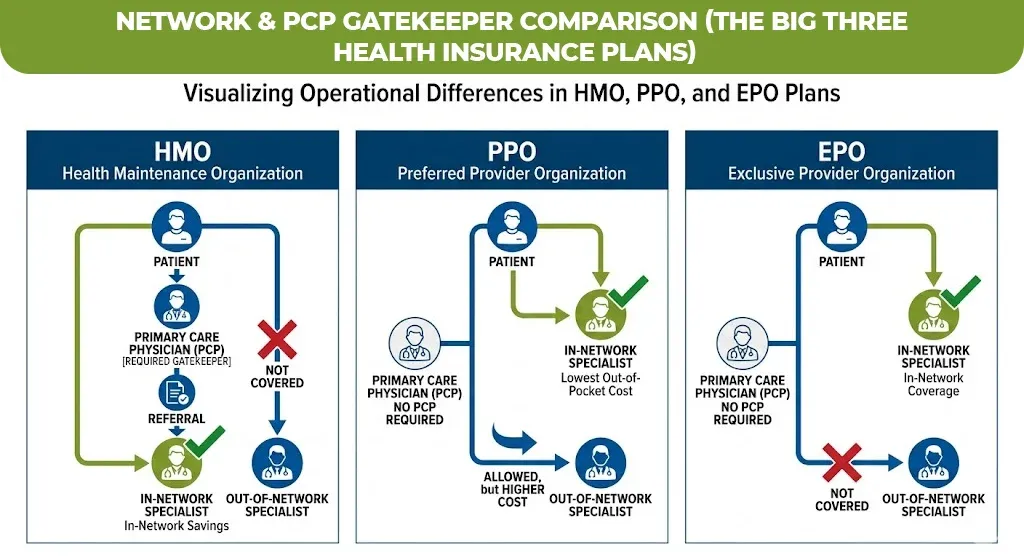
Like all health strategies, getting in-network care is best to keep your out-of-pocket costs low. Nevertheless, unlike HMO strategies that will not cover any portion of your expense if you look for out-of-network care (other than in a covered emergency situation), you can get out-of-network care when traveling out of your regular plan network location with a PPO policy.
Cost-conscious people ought to consider a couple of downsides to PPO plans that might make getting care more expensive. While they're flexible and convenient, PPO plans have higher premiums. According to KFF, PPO strategies had the highest yearly premiums compared to HMOs and point-of-service plans (POS) in 2023. You'll likewise have to pay more expensive medical costs if you get care from an out-of-network service provider.
If you do have a deductible, it's most likely to be more pricey than other plan types. While your insurance company will share the expense with you, you'll likely pay a higher coinsurance portion for out-of-network service providers. When you go to an in-network company, they'll file your claim to your medical insurance company on your behalf.
PPO insurance policy holders might discover the claim filing process complicated if they're not used to it or time-consuming if they often need out-of-network care from a professional. In 2023, the average annual premium for a group PPO plan was $8,906 for self-only protection and $25,228 for household coverage2. Companies contributed $7,399 toward a self-only plan, and workers contributed $1,507.
Evaluating PPO and HMO Insurance
The typical deductible for PPO plans was $1,281. As discussed above, PPO prepares acquired on the ACA markets also have an optimum out-of-pocket limit of $9,450 for self-only coverage and $18,900 for family plans.
Yes No Yes No Some plans do. Most plans do. Whether you have an HMO or PPO plan, you can take advantage of a health reimbursement arrangement (HRA) to lower out-of-pocket medical expenditures.
Just companies can release and contribute towards an HRA. Employers use an HRA to provide their staff members a month-to-month allowance to spend for medical costs. As soon as a worker buys an eligible product or service, they send documents showing evidence of purchase, and their employer repays them as much as their allowance quantity.
Smart Wealth Strategies with Life Insurance
(MEC). (ICHRA): An ICHRA is likewise a stand-alone HRA, but it's available to employers of all sizes and has no contribution limits.
They should have a certifying kind of individual health protection to get involved. Employers can set various allowances based on staff member classes for included customization. Group coverage HRA (GCHRA): Likewise called an integrated HRA, a GCHRA is for employers of any size who offer a group health insurance. Just workers registered in their company's group plan can participate.
While they have no optimum contribution limitations, the IRS doesn't permit compensations for month-to-month premiums. No matter whether it's utilized in coordination with an HMO or PPO strategy, there's an HRA that can assist workers pay for their out-of-pocket medical costs and, in some cases, their health insurance coverage premiums. An HRA is a popular alternative option over standard health advantages because they're affordable for employers and versatile enough for every single staff member.
Evaluating PPO and HMO Insurance
An HMO might be your best option if you're looking for a plan with a low premium. Nevertheless, a PPO plan supplies additional flexibility if you need more control over your healthcare. That's why investigating these plans carefully, including their pros, cons, and typical costs, is the best primary step you can take previously deciding.
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, however it's readily available to companies of all sizes and has no contribution limits.
They need to have a qualifying kind of individual health coverage to participate. (GCHRA): Likewise understood as an incorporated HRA, a GCHRA is for employers of any size who offer a group health strategy. Only staff members registered in their employer's group strategy can take part.
Low-Cost Plan Choices for US Veterans
While they have no maximum contribution limits, the internal revenue service does not enable compensations for regular monthly premiums. No matter whether it's used in coordination with an HMO or PPO plan, there's an HRA that can assist staff members spend for their out-of-pocket medical expenses and, sometimes, their health insurance coverage premiums. An HRA is a popular alternative option over standard health advantages because they're economical for companies and versatile enough for every single employee.
An HMO may be your best option if you're searching for a plan with a low premium. However, a PPO strategy supplies extra versatility if you require more control over your healthcare. That's why researching these strategies carefully, including their pros, cons, and average costs, is the very best initial step you can take in the past deciding.

Latest Posts
Comparing PPO and HMO Health Insurance Explained
The Way Whole Life Insurance Works in 2026
Indexed Universal Life Benefits for Retirement